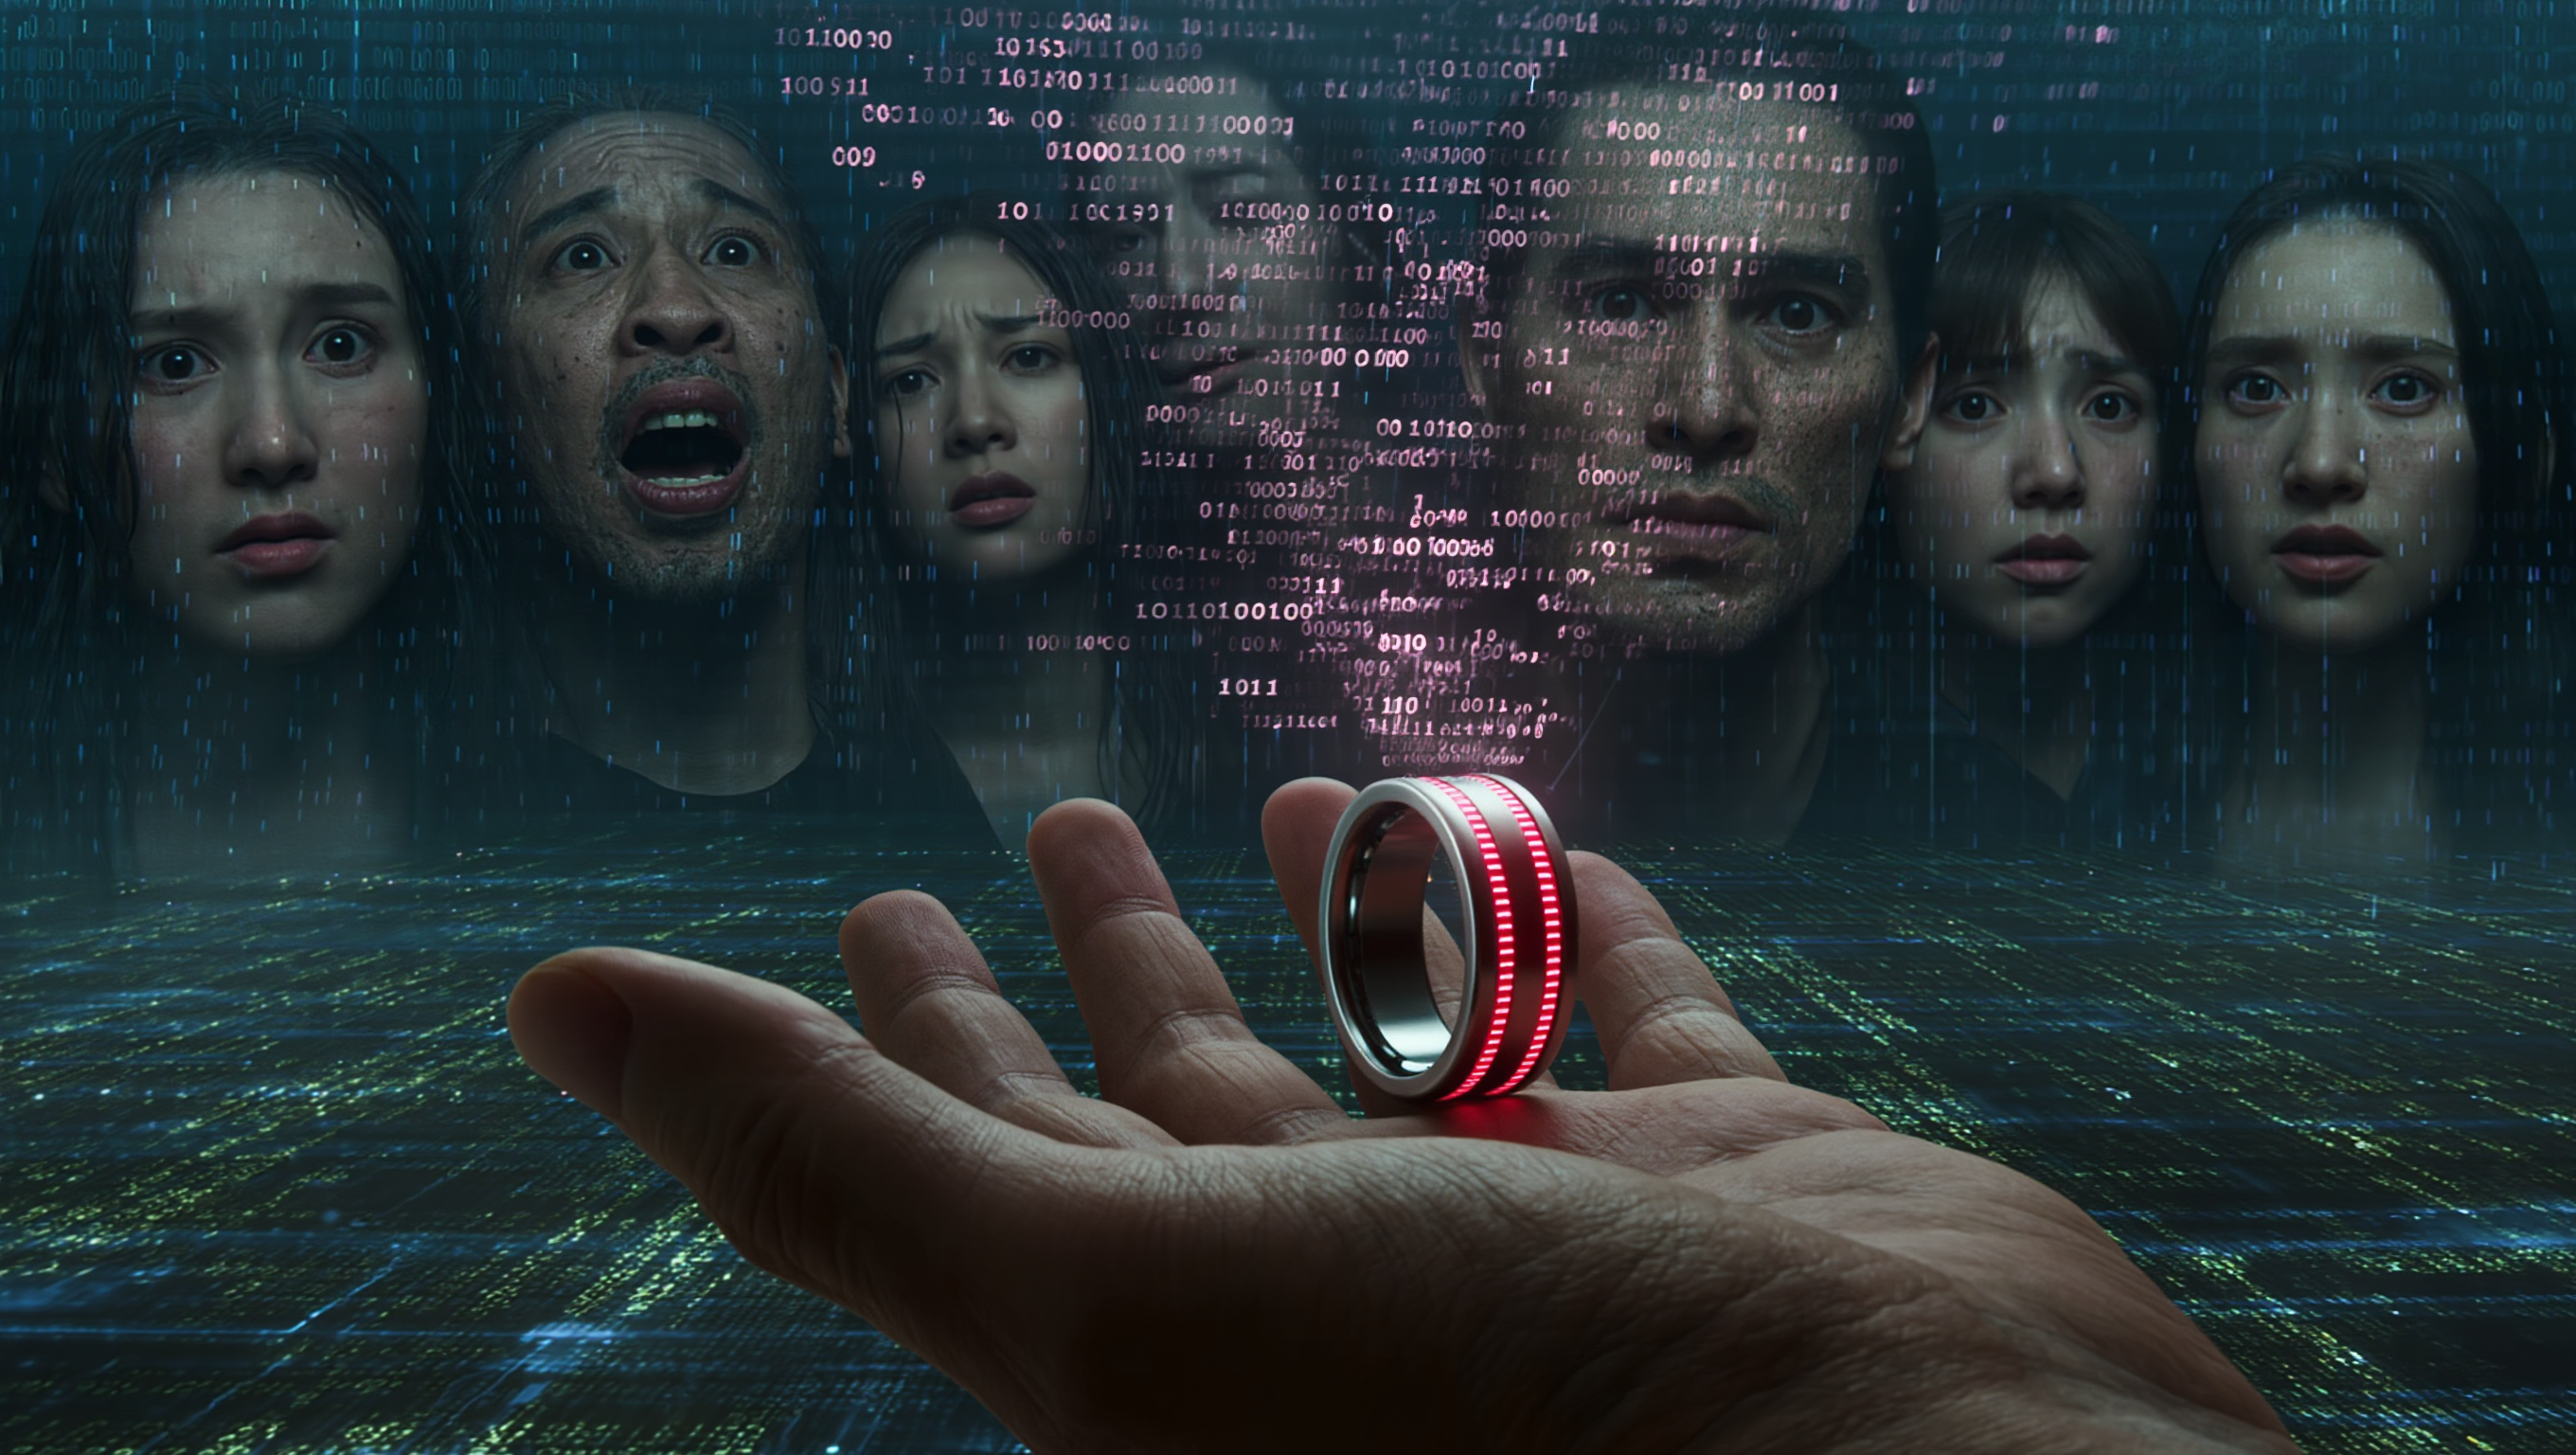
When the world's economic rulebook is rewritten, the pens won't be held in Washington or Brussels. They'll be gripped in Nairobi, São Paulo, and New Delhi—and the ink is already drying.
The world did not end with a bang, but with a failed Treasury auction. For nearly a century, the United States dollar has been the oxygen of global commerce—invisible, essential, and entirely taken for granted. Yet here we stand in 2026, watching the "exorbitant privilege" of the West curdle into an exorbitant liability whilst 85% of humanity quietly builds a new room at an entirely different table.
This isn't speculation. This is the present, accelerating.
The Numbers Don't Lie, Even When We Do
The empire's books are a mess, and everyone knows it. The United States faces an $8 trillion refinancing burden, whilst France's public debt has ballooned to a peacetime record of 117.4% of GDP. Global debt now stands at $300 trillion—triple the world's entire economic output—with 40% of the $100 trillion bond market requiring refinancing by 2027. This isn't a hypothetical crisis; it's a refinancing timebomb ticking louder with each quarterly report.
Meanwhile, the so-called "emerging economies" are doing anything but merely emerging. They're arriving. The BRICS+ bloc now commands 41% of global GDP on a purchasing-power-parity basis, outstripping the G7. China has become the largest trading partner of more than 90 countries, whilst the renminbi now accounts for 3.17% of global payments, up from a peripheral status just a few years ago. The dollar's share of global foreign exchange reserves has tumbled to just under 60%—a two-decade low.
One-fifth of oil transactions now occur in non-dollar currencies. Saudi Arabia—a long-standing pillar of the petrodollar system—is contemplating yuan-denominated oil futures. Bangladesh settles nuclear power plant payments in yuan. Russian oil trades in local currencies.
But these are merely symptoms. The real revolution is infrastructural.
Building a New Room Entirely
The mBridge platform—a multi-central bank digital currency system linking China, Hong Kong, Thailand, the United Arab Emirates, and Saudi Arabia—enables real-time cross-border payments that bypass SWIFT entirely. BRICSpay processes transactions in multiple non-dollar currencies. The New Development Bank now provides infrastructure financing with notably fewer conditionalities than the World Bank, its loan portfolio swelling across Africa and Southeast Asia.
Perhaps most tellingly, BRICS countries are finalising plans for a grain exchange that will consolidate 30-40% of global cereal trade—1.24 billion tonnes of grain representing 44% of world production. Crucially, this exchange enables trading in local currencies, wresting price-setting power from Western commodity platforms. When you control food, you don't just feed people—you feed power itself.
This is not a future scenario. This is happening now.
Geneva, November 2028: The Morning the Leverage Evaporated
Sofia Okafor adjusted her earpiece as she entered the Palais des Nations, the weight of the moment pressing against her chest. As chief negotiator for the African Continental Free Trade Area, she had watched the Western debt crisis that erupted in spring 2027 transform from someone else's problem into her continent's opportunity.
The emergency G7 summit had produced nothing but platitudes. Washington had quietly begun discussions with Beijing about a "monetary stability framework"—diplomatic code for "please keep buying our bonds". But the Global South had other ideas.
The BRICS Summit in São Paulo that October had announced "The Unit"—a basket reserve currency backed 40% by gold and 60% by BRICS national currencies. Brazil's President had been blunt: "For decades, we've absorbed your inflation, weathered your interest rate hikes, and restructured our economies to service debts denominated in your currency. That era is over."
Now, Sofia sat across from representatives of the IMF and World Bank, institutions that suddenly looked less like architects of global stability and more like relics from a bygone age. The IMF deputy director was mid-sentence when she interrupted.
"With respect, Dr Hartmann, we're not here to negotiate terms. We're here to inform you of them."
She opened her tablet, displaying a document quietly circulated amongst Global South finance ministers: fifty-three nations representing 4.2 billion people had signed a declaration to jointly reduce dollar reserve holdings by 40% over three years, redirect sovereign bond issuance towards regional development banks, and implement commodity-linked trade frameworks bypassing dollar settlement.
"You'll trigger a liquidity crisis," Hartmann calculated.
"You already have one," Sofia replied. "You just haven't admitted it yet. We've been building alternatives. You need us more than we need you."
History, Sofia thought, doesn't always arrive with fanfare. Sometimes it's just a room of uncomfortable people, realising their leverage has evaporated.
The Signals Flashing Red
If this seems far-fetched, consider what's already visible on your horizon:
Financial fragility indicators:
Watch U.S. Treasury auctions for weakening demand from traditional buyers like Japan and China. France's yields already exceed those of Spain, Italy, and Greece. Sustained inflows to emerging market assets whilst developed market bonds struggle would mark a historic reversal.
De-dollarisation milestones:
The mBridge platform has processed pilot transactions; scaling to hundreds of billions would represent a genuine SWIFT alternative. The renminbi's steady growth towards 5-10% of global payments would cement the yuan as a legitimate reserve currency.
Institutional displacement:
The New Development Bank's lending portfolio relative to World Bank and IMF programmes indicates the balance of power shifting. BRICS+ has grown from five to ten members; further additions would command a majority of the global population and GDP.
Geopolitical realignments:
The Voice of Global South Summit already convenes 134 nations representing 80% of humanity. The African Continental Free Trade Area encompasses 1.3 billion people and $3.4 trillion in GDP—the world's largest trading bloc by membership. Universities in Singapore, Mumbai, and São Paulo are now top choices for economics students from emerging nations, replacing their traditional preference for Harvard and LSE.
The Question Nobody Wants to Ask
The real question isn't whether the Global South could set the rules. It's whether the West will gracefully adapt to a multipolar order or cling to hegemonic privilege until the architecture collapses beneath it.
Climate change is rewriting the geography of habitability. Demographic destiny favours the South. Technological diffusion has eroded the North's productivity monopoly. Resource nationalism is concentrating leverage in commodity-rich nations. And mounting debt has transformed the West from creditor to supplicant.
When Western financial architecture wasn't designed for their realities, Dr Anya Sharma explained, when your prescription for every economic illness is austerity and privatisation, you create resistance. "We're not rejecting globalisation—we're democratising it".
The next financial crisis won't be contained by institutions designed to fight the last war. When refinancing costs spike, when bond auctions fail, when currency crises cascade across overleveraged economies—who holds the lifeline? The answer increasingly lies in Beijing, not Washington; in New Delhi, not Brussels; in Riyadh, not London.
It is tempting, especially in Britain, to watch all this like a distant pageant: intriguing, faintly alarming, somebody else's business. That is exactly how empires lose the plot—by confusing the comfort of familiarity with the stability of reality.
So here's the uncomfortable question that demands your answer: When 85% of humanity has had virtually no say in designing the global economic system that shapes their lives, is rebalancing truly unjust—or merely just? And when the Global South's moment arrives—not if, but when—which side of history will the West choose: partnership in a multipolar world, or nostalgia for a unipolar fantasy it can no longer afford?
The world needs your what-ifs. Join us at ThinkingIf.com—where we don't just predict tomorrow, we imagine better alternatives. Subscribe for exclusive scenario deep-dives, join our weekly provocations, and help build the futures we deserve rather than those we're handed. Because the future belongs to those who see it coming.